
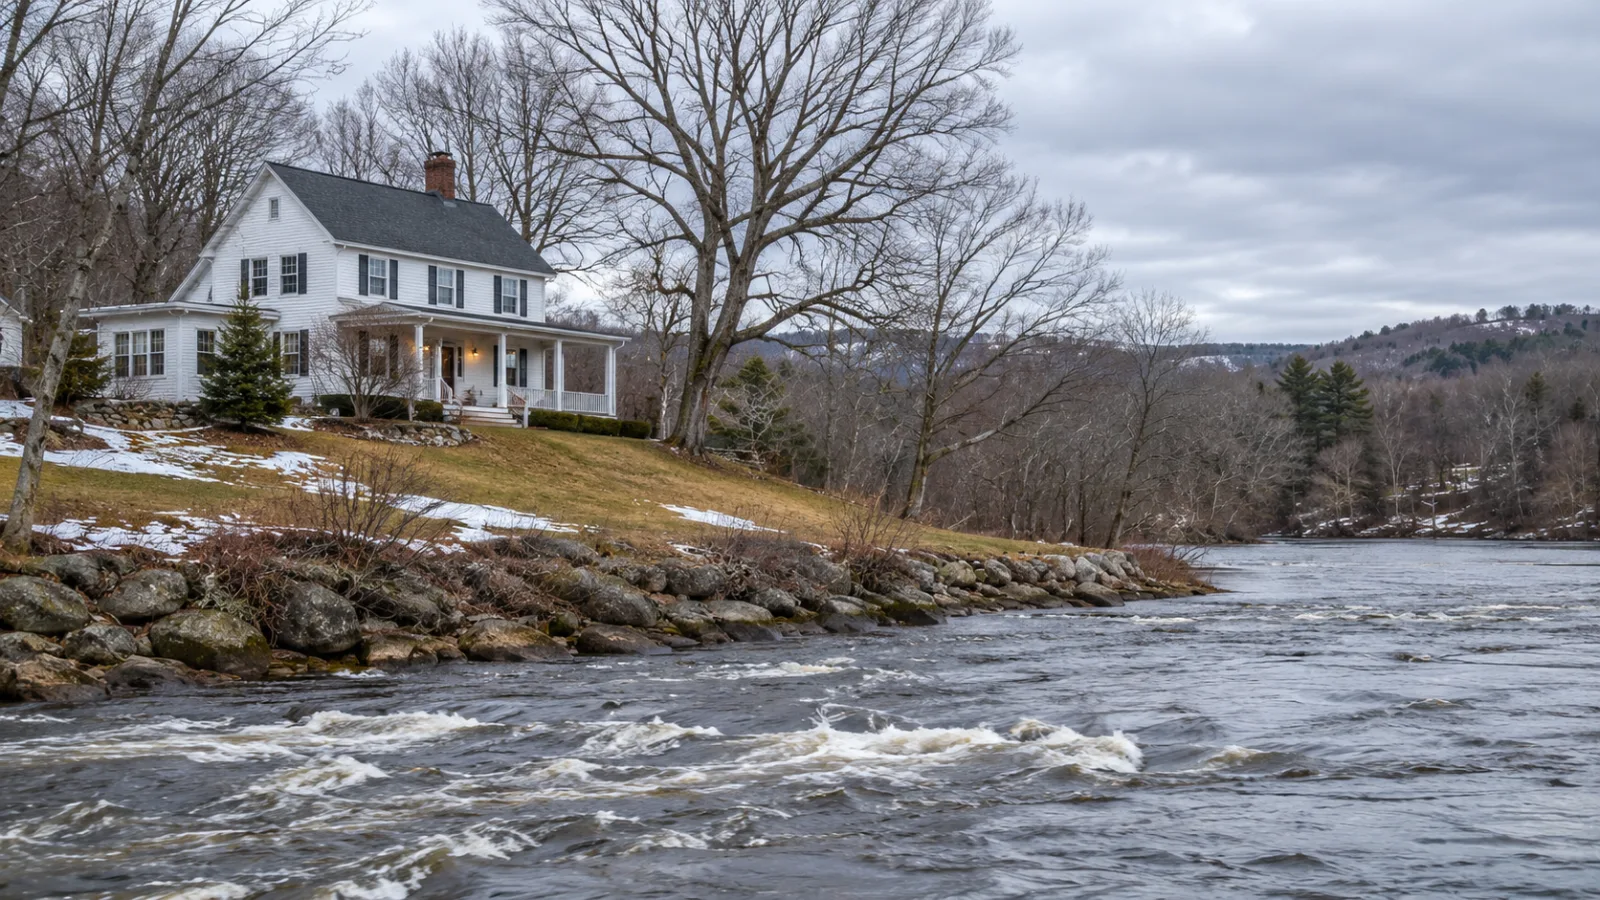
Flood insurance in New Hampshire is required only when a building sits in a FEMA Special Flood Hazard Area (a zone starting with A or V on the flood map) and the mortgage is federally backed or regulated. Standard homeowners policies exclude flood damage, so a buyer anywhere else decides for themselves, and since 2024 NH sellers must disclose the flood zone.
Flood risk is one of the questions in our New Hampshire home buyer guide that's worth answering before the offer, not after the inspection.
On this page
- When is flood insurance required in New Hampshire?
- What does New Hampshire law make sellers disclose about flooding?
- Should you buy flood insurance outside a flood zone in NH?
- Frequently asked questions
When is flood insurance required in New Hampshire?
Flood insurance is required in New Hampshire when a lender that is federally regulated or federally insured makes a loan on a building in a Special Flood Hazard Area. That rule comes from the federal Flood Disaster Protection Act of 1973, not from state law, and it applies to the building, not the contents.
A cash buyer has no lender to enforce it, so the choice is entirely theirs. Few owners buy coverage voluntarily: the share of homes with flood insurance New Hampshire officials reported in 2021 was under 2 percent, about 7,700 NFIP policies statewide. A lender can also ask for a flood policy in a lower-risk zone if it wants to, and some do on low riverfront lots. To find the zone, search the address on FEMA's Flood Map Service Center, which is free. A zone beginning with A or V is high risk; X is moderate to low.
What does New Hampshire law make sellers disclose about flooding?
New Hampshire law makes sellers of one- to four-family homes disclose in writing whether the property is in a federally designated flood hazard zone, under RSA 477:4-d as amended by HB 1320 (in effect July 19, 2024). The same bill added a flood paragraph to the RSA 477:4-a notice buyers sign before the purchase and sales agreement, effective January 1, 2025.
The disclosure tells you the zone, not the history. Ask the seller directly whether the basement has taken water, whether a flood claim has ever been paid, and whether there is a sump pump and when it last ran. Our guide to NH seller disclosure requirements lists every required item, and our answer on what a P&S is explains how the disclosures fit the contract.
Should you buy flood insurance outside a flood zone in NH?
Buying flood insurance outside a flood zone in NH is worth pricing whenever a house sits low near a river, a brook or a lake. FEMA says nearly 25 percent of National Flood Insurance Program claims come from properties outside the mapped high-risk areas, and its more recent materials put the share higher. A homeowners policy pays nothing for rising water. For the 2024 flood declaration, see which NH counties are in FEMA DR-4799.
In our part of the state the risk follows the rivers. In Plymouth, both the Pemigewasset and the Baker run high with spring snowmelt, and the same is true of the Pemi's tributaries through Campton and Thornton. On the lakes, plenty of shorefront houses sit well above the water and outside the mapped zone, while low lots, coves and river-mouth parcels can sit inside it. Our Lakes Region waterfront guide covers flood insurance alongside docks, shoreland rules and septic.
Two details catch buyers out. A new NFIP policy normally takes effect 30 days after purchase, unless it is bought in connection with making, renewing or extending a federally backed loan, so it can't be bought the week before closing as an afterthought. And NFIP coverage stops at $250,000 for a one-to-four-family building and $100,000 for contents, so higher-value lake homes often add private excess flood coverage.
Frequently asked questions
Does homeowners insurance cover flooding in New Hampshire?
Homeowners insurance in New Hampshire does not cover flood damage from rising water, overflowing rivers or lakes, or surface runoff; FEMA notes that most homeowners and renters policies exclude it. Flood cover comes from a separate NFIP or private flood policy. Some homeowners policies offer a water backup endorsement for sewer or sump failures, which is not the same thing.
How do I find out if a house is in a flood zone in NH?
Search the address on FEMA's Flood Map Service Center, which shows the flood zone on the current Flood Insurance Rate Map for free. The seller's RSA 477:4-d disclosure should state the zone as well. If the map is unclear for a specific building, an elevation certificate from a surveyor settles it and also helps price the policy.
Can you buy flood insurance anywhere in New Hampshire?
NFIP flood insurance can be bought in any New Hampshire town that takes part in the National Flood Insurance Program, through a regular insurance agent, and private flood policies are available too. Get a quote during the inspection period so the cost goes into your budget before your contingencies expire. Our buyers page is the place to start that conversation with us.