
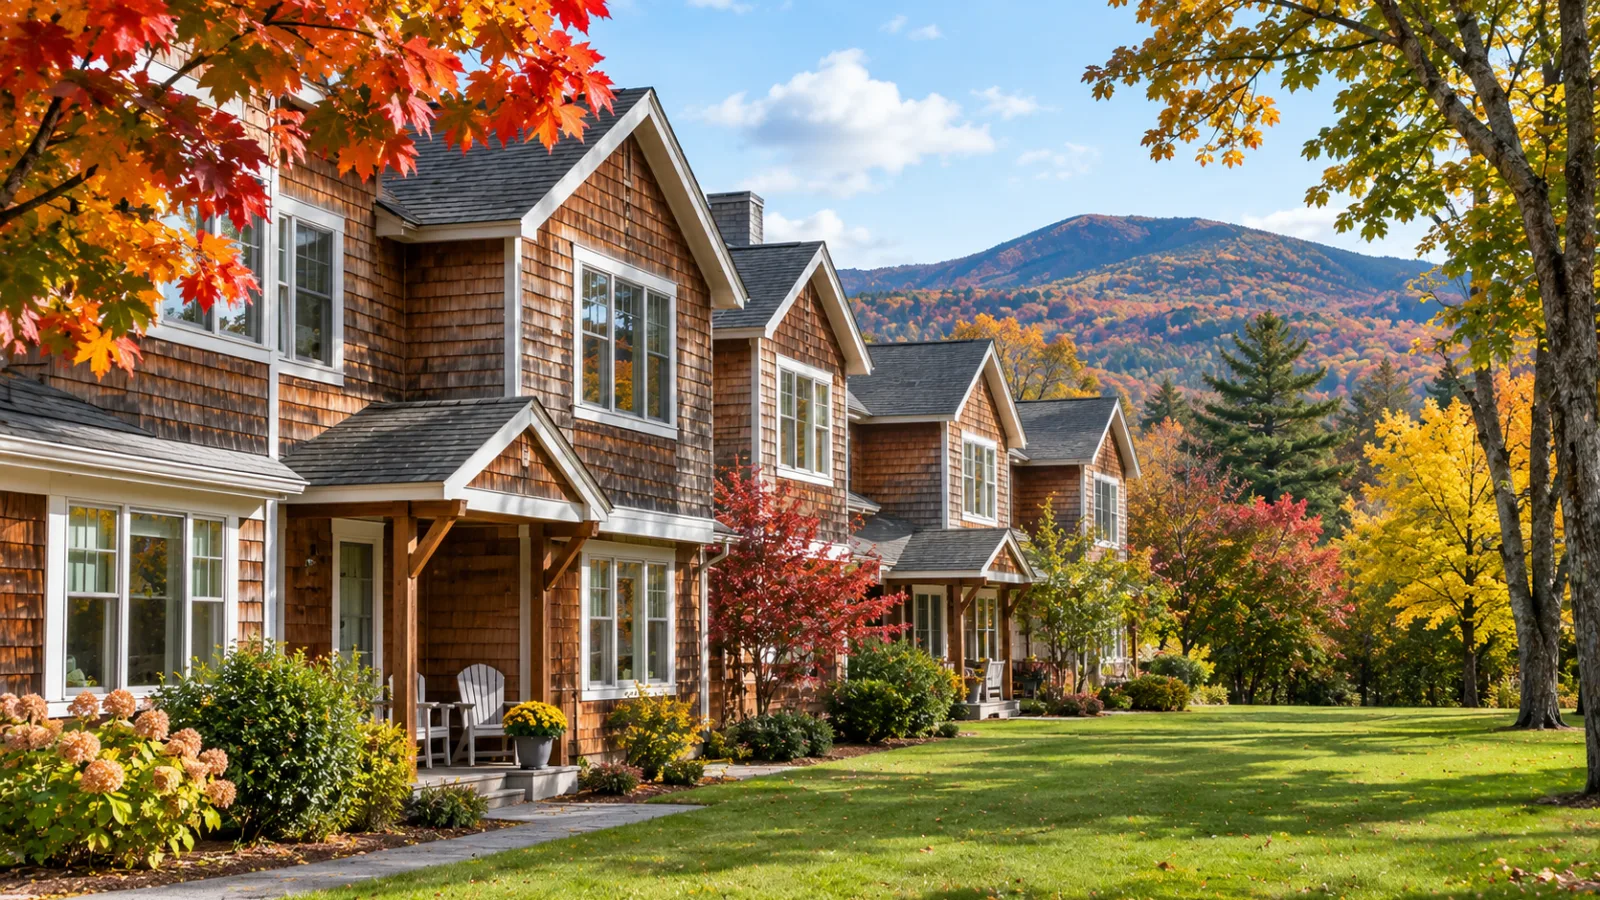
The difference between a PUD and a condo is what you own. In a condominium you own your unit plus an undivided percentage of the common areas shared with every other owner, under New Hampshire's Condominium Act (RSA 356-B). In a planned unit development (PUD) you own your house and the lot under it outright, and a homeowners' association owns the common areas. The building style tells you nothing: a townhouse can be either one, and so can a detached house.
Key takeaways
- Ownership decides it, not looks. Fannie Mae's Selling Guide says plainly that "zoning is not a basis for classifying a project or subdivision as a PUD"; the recorded documents are what count.
- New Hampshire condos are governed by RSA 356-B, the Condominium Act, which gives resale buyers a right to the association's documents within ten days of a written request (RSA 356-B:58).
- Lenders review condo projects more closely. Fannie Mae waives project review for most PUD units, and for detached condos and very small condo projects, while units in larger attached condo projects go through a project review. FHA loans on condos need project approval or a single-unit approval.
- Insurance differs. A condo owner usually carries an HO-6 policy alongside the association's master policy; a PUD owner usually insures the whole house with an HO-3.
- "PUD" also means something else in New Hampshire: a zoning tool towns can adopt under RSA 674:21. A subdivision approved as a PUD under zoning isn't automatically a PUD to your lender.
We sell condos, townhomes and association homes from Waterville Valley to Lincoln and the Lakes Region, and the condo or PUD question comes up most often when a buyer's lender asks it. This guide explains the difference, what New Hampshire condo law says, and what each form means for your mortgage, insurance and monthly costs.
In this guide
- What is the difference between a PUD and a condo?
- Is a townhouse a PUD or a condo?
- What does New Hampshire condominium law say?
- What is a planned unit development in New Hampshire zoning?
- Condo vs PUD: how does financing differ?
- HO-6 vs HO-3: how does insurance differ for a condo and a PUD?
- Are HOA fees higher in a condo or a PUD?
- PUD or condo: which is better for a buyer?
- Frequently asked questions
What is the difference between a PUD and a condo?
A condo and a PUD differ in who owns the land and the shared spaces, and that is the whole of the planned unit development vs condo distinction. Both usually have an association, monthly or quarterly dues, and rules. The ownership structure underneath them is different, and that structure is what lenders, insurers and the law care about.
In a condominium, each owner holds title to a unit and a fractional, undivided interest in the common areas: the land, the roofs and outside walls in many cases, the roads, the pool. The declaration assigns each unit its percentage, in proportion to the unit's size or value or in equal shares (RSA 356-B:17). Nobody owns "their" patch of the lawn; every owner owns a share of all of it. Some areas, such as a deck or a parking space, can be limited common areas assigned to one unit while still being common property.
In a PUD, each owner holds title to a lot and the house on it, much like an ordinary single-family home. The association, usually a nonprofit corporation, owns the common property (roads, open space, a clubhouse) and charges mandatory dues to maintain it. Fannie Mae's definition, in Selling Guide B4-2.3-01 (topic dated August 5, 2026), requires that membership in the association be automatic, that the assessments be mandatory, that the association own and maintain the common property, and that the unit not be legally part of a condominium.
PUD vs condominium: side-by-side comparison
| Condominium | Planned unit development (PUD) | |
|---|---|---|
| What you own | Your unit, plus an undivided percentage of all common areas | Your lot and the house on it |
| Who owns common areas | All unit owners together, by percentage | The homeowners' association |
| Governing law in NH | Condominium Act, RSA 356-B, plus the recorded declaration | The recorded covenants and the association's own bylaws |
| Exterior and roof | Often common area, maintained by the association | Usually yours, unless the covenants say otherwise |
| Insurance | Association master policy, plus your HO-6 | Your HO-3 on the house; the association insures common property |
| Fannie Mae project review | Required for most attached condo projects; waived for detached condos and two- to four-unit projects | Waived for most PUD units |
| FHA | Project approval or single-unit approval needed | Not subject to FHA's condominium approval process |
| Dues typically cover | Common-area upkeep, often exterior, roofs, master insurance, reserves | Roads, plowing, open space, amenities |
| Resale documents | Statutory right under RSA 356-B:58 | Whatever the covenants and bylaws provide |
The table describes the typical case. The documents can move items between columns, especially exterior maintenance, so the declaration or covenants always win over a general rule.
Is a townhouse a PUD or a condo?
A townhouse can be either a PUD or a condo; the word describes the building, not the ownership. Attached townhouse communities are often condominiums, but some are PUDs where each owner holds title to the lot under their section of the building. Detached homes can be condominiums too: a "site condominium" makes each house and its yard a unit, with the roads and open land as common area. Lenders treat a site condominium as a condo, not a PUD, because its units were legally created under a condominium declaration.
How to tell which one you're looking at:
- Read the deed. A condo deed conveys "Unit X of [name] Condominium" and refers to a recorded declaration. A PUD deed conveys a numbered lot on a recorded subdivision plan.
- Look for the declaration. A condominium is created by recording a declaration and its site and floor plans at the county registry of deeds. No condominium declaration usually means it isn't a condo.
- Check the tax card. The town's assessing record usually shows whether the parcel is a condo unit or a land lot.
- Ask the listing agent and the association. MLS fields aren't always right. When it matters for financing, the lender will want the documents anyway.
PUD or condo: what does the MLS listing say?
An MLS listing names a property type, such as Condominium, Townhouse or Single Family Residence, but that field describes the property for searching, not its legal form. A site condominium can be listed as a single-family home, and a townhouse on its own platted lot can be listed as a condo. Before you choose a loan program, confirm the legal form from the deed and declaration.
What does New Hampshire condominium law say?
New Hampshire condominium law is the Condominium Act, RSA chapter 356-B. It governs how a condominium is created, how ownership of the common areas is split, how the association runs, and what a seller and the association owe a buyer. The NH Condominium Act (often shortened to the NH condo act) applies only to condominiums; an HOA in a PUD runs under its own recorded covenants and bylaws, not under 356-B.
The provisions buyers run into most:
- Ownership shares. The declaration allocates each unit an undivided interest in the common areas, based on size, value or equal shares, and that allocation can't be changed except as the Act allows (RSA 356-B:17). That share usually sets how common expenses are divided.
- Termination. If a condominium is ever terminated, the owners hold the property as tenants in common in proportion to those same shares (RSA 356-B:34). It is rare, but it is why the percentage matters.
- Resale documents. Under RSA 356-B:58, a resale buyer is entitled, before the contract date, to a defined package from the association, which must answer within ten days of a written request: unpaid assessments on the unit, capital and major maintenance spending expected over the current and next two fiscal years, reserves, the latest income statement and balance sheet, pending lawsuits, insurance, the declaration, bylaws and rules, and fees and special assessments for the last three years.
- The declaration and rules. Leasing, pets, short-term rentals and alterations are governed by the declaration, bylaws and rules adopted under the Act, and they vary widely from one association to the next.
What should a buyer check under the NH condo law?
A buyer should request the RSA 356-B:58 package before signing a purchase agreement, because the statute frames it as information for a prospective buyer before the contract date and the association has ten days to answer. If time is short, make the offer conditional on reviewing the package.
Read the reserves and the capital plan together: a big roof or road project with thin reserves usually means a special assessment. Read the rental rules if you plan to rent. Our guide to Lincoln condos near Loon Mountain walks through the whole document package with a ski-town example.
What is a planned unit development in New Hampshire zoning?
In New Hampshire zoning, a planned unit development is one of the "innovative land use controls" a town may adopt under RSA 674:21. It lets a planning board approve a whole development as a unit, with flexible lot sizes, clustering or mixed uses, in exchange for open space or other conditions. RSA 674:21-a makes the open-space designations and other restrictions in an approved PUD enforceable.
That zoning meaning is different from the lender's meaning, and confusing them is common. A development a town approved under its PUD ordinance might be built as a condominium, as a PUD in the lender's sense, or as an ordinary subdivision with no association at all. Fannie Mae's guide addresses this directly: a project that is only zoned as a PUD, with no common property, required association or assessments, is not a PUD for mortgage purposes. Ask what the recorded documents created, not what the zoning approval called it.
Condo vs PUD: how does financing differ?
PUD and condo financing differ mainly in how much the lender reviews the association, and condos get more scrutiny. Under Fannie Mae's waiver of project review, units in new and established PUD projects generally don't need a project review (PUDs of manufactured homes on a community land trust, ground lease or shared-equity arrangement are the exception). The lender still applies its property rules, but the association itself isn't underwritten.
Fannie Mae waives the review for some condos too: detached condo units, units in two- to four-unit condo projects, and units in five- to ten-unit projects that aren't part of a larger development or master association.
Units in larger attached condo projects, which describes most resort condo buildings, go through a project review, which looks at the association's budget and reserves, insurance, delinquent dues, litigation, owner-occupancy and whether any one entity owns too many units. Resort condos run into a further set of rules about condo-hotel features such as front desks and rental pools. A building that fails is called non-warrantable, and buyers there need a portfolio loan, a non-QM loan or cash. Our Lincoln condo guide lists those condo-hotel tests in full.
FHA loans have their own condo process. A condo unit needs either a project on FHA's approved list or a single-unit approval, which HUD grants only when the project meets its own set of eligibility rules, including a cap on how many units in the project can carry FHA-insured loans. VA loans have their own condominium review as well. If you are using FHA or VA, ask the lender to check the specific association before you sign a purchase agreement, not after.
HO-6 vs HO-3: how does insurance differ for a condo and a PUD?
A condo owner usually carries an HO-6 policy and a PUD owner usually carries an HO-3, because they own different things. In a condominium, the association's master policy insures the building and common areas, and your HO-6 covers what the master policy doesn't: interior finishes and upgrades (depending on the master policy), your belongings, liability, and loss assessments. In a PUD, you own the house, so you insure all of it with an ordinary homeowner's policy, and the association insures only its common property.
The trap in condos is the master policy's deductible. Fannie Mae's master insurance requirements (topic dated August 5, 2026) require a financed condo buyer to carry a unit-owner (HO-6) policy when the master policy has a per-unit deductible, and cap that deductible at $50,000 per unit. Ask the association for the declaration page before you get an insurance quote. In a PUD, check whether the covenants require a particular level of coverage or a matching exterior after a loss.
Are HOA fees higher in a condo or a PUD?
Condo dues are usually higher than PUD dues, because a condominium association typically pays for more: often the roofs, siding and exterior maintenance, the master insurance policy, and reserves to replace all of it. A PUD association often maintains only roads, plowing and shared amenities, and the owner pays for their own roof and insurance directly. Compare total cost, not just dues; a lower PUD fee plus your own HO-3 and roof reserve can land close to a condo fee.
Property taxes work the same way in both: the town assesses your unit or lot and bills you directly at its rate. Some communities add a separate layer. Waterville Estates in Campton, a hillside community of about 700 homes and condos, has its own association dues and a village district tax on top of the town's. Our guide to New Hampshire property taxes explains village districts and how rates are built.
PUD or condo: which is better for a buyer?
Neither a PUD nor a condo is better in general; each suits a different kind of ownership. A condo usually costs more in dues but asks less of you. Exterior upkeep, plowing and insurance on the structure are handled for you, which suits a ski or lake second home you visit on weekends. A PUD gives you more control over your house and usually an easier mortgage, at the price of maintaining and insuring the building yourself.
In our experience the deciding questions are practical:
- What loan are you using? If it's FHA, VA or a low-down-payment conventional loan, a PUD or an approved condo project keeps more options open.
- Will you rent it? Check the declaration or covenants; condo associations in resort towns often have detailed rental rules, and some PUD covenants do too.
- Who maintains the roof and siding? Read it in the documents, then compare the dues and reserves with what you'd spend yourself.
- How healthy is the association? For a condo, the RSA 356-B:58 package answers this. For a PUD, ask for the budget, reserves and minutes anyway.
You can browse every association by town on our New Hampshire condos page, including the Waterville Valley condo communities and Lincoln condos. When you find one, we can pull the documents and tell you what the association actually is before you make an offer; start on our buyers page.
Frequently asked questions
What is the difference between a PUD and a condo?
In a condo you own your unit and an undivided percentage of all the common areas, shared with the other owners. In a PUD you own your house and its lot, and a homeowners' association owns the common areas. The recorded documents decide which one a property is, not the building style.
Is a PUD or a condo easier to finance?
A PUD is usually easier to finance. Fannie Mae waives project review for most PUD units, while units in larger attached condo projects need a project review of the association's finances, insurance and occupancy, and FHA loans need the condo project approved or a single-unit approval.
What is the NH Condominium Act?
The New Hampshire Condominium Act is RSA chapter 356-B, the state law that governs how condominiums are created and run. It sets how common-area shares are allocated, how associations operate, and what documents a resale buyer can demand under RSA 356-B:58.
Does New Hampshire condo law apply to an HOA?
No, not to an HOA in a PUD or ordinary subdivision. RSA 356-B applies only to condominiums. A homeowners' association outside a condominium is governed by its recorded covenants, its bylaws and general nonprofit and contract law.
Do I need HO-6 or HO-3 insurance?
A condo owner usually needs an HO-6, which covers the interior, belongings and liability alongside the association's master policy. A PUD owner usually needs an HO-3 on the whole house. The association's documents and master policy settle what you must insure.
Can a single-family home be a condo?
Yes. A detached house can be a unit in a "site condominium," where each house and its yard is a unit and the roads and open land are common area. The deed and declaration show whether a house is a condo unit or a lot.
Are condo fees higher than PUD fees?
Usually, because a condo association often covers exterior maintenance, the master insurance policy and reserves, while a PUD association often covers only roads and shared amenities. Compare the total cost of ownership, including the insurance and maintenance a PUD owner pays directly.